


How to Win a Home Without the Highest Offer
By Chris & Sue Kull, The Kull Group powered by Keller Williams Wellington
Quick answer: You can win a home without the highest offer by giving the seller two things: confidence that you will close, and a solution to whatever problem they are trying to solve. Sellers weigh three things: the price, the proof that you can close, and how well your terms fit their plan for after the sale. A lower offer can compete when it is stronger on proof and plan. We recently helped buyers in Loxahatchee win a home over cash offers that were $5,000 to $10,000 higher. Call or text us at 561-440-0777 to talk through your next offer.
Why the biggest number doesn't always win
If you assume the seller simply takes the highest offer, you may be competing on only one of the things the seller is weighing. In our experience, after more than 30 years and over 1,000 homes sold, sellers are really choosing the offer they trust to close. A higher price means nothing if the deal falls apart weeks later over an inspection dispute, a low appraisal or a loan that never gets approved.
That is part of why cash offers appeal to sellers. A cash offer with no financing contingency takes the risk of a loan denial off the table. It does not remove every risk, because inspection, appraisal, title and other contract terms can still affect a cash sale. So if you are financing, your job is not always to outbid cash. Your job is to reduce the seller's doubts as far as your financing realistically allows, and then give the seller a reason to prefer you.
The story: how Stephen and Vanessa won over higher cash offers
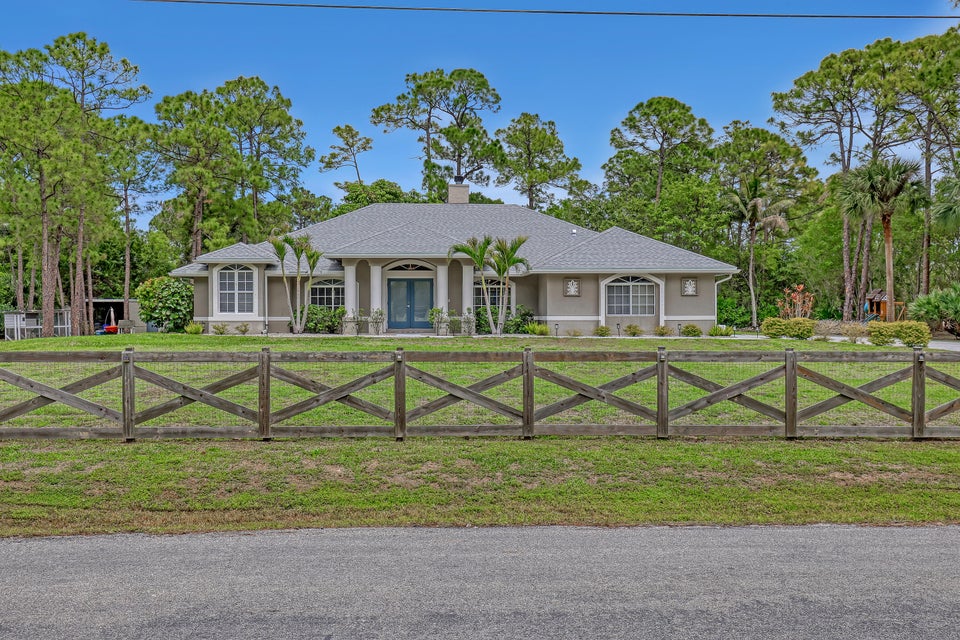
Stephen and Vanessa found a home they loved in Loxahatchee, and they weren't the only ones. They were up against cash offers that were $5,000 to $10,000 higher than theirs.
We did two things. First, we shortened their inspection period and their loan approval period considerably, so the sellers would know within days that this deal was going to close. Second, before writing the offer, I called the listing agent and asked what else the sellers needed beyond price. Their new home wasn't ready yet, and they needed somewhere to stay after closing.
Stephen and Vanessa offered a 30-day post-closing occupancy agreement. The sellers chose them. Their offer wasn't the highest, but it was strong on proof and it fit the sellers' plan. Stephen and Vanessa gave us permission to share their story.
Price, proof and plan: how sellers actually compare offers
When we sit on the seller's side of the table, offers are not compared on price alone. They are compared on three separate questions:
- Price: What is the number, and what will the seller net after any credits or concessions?
- Proof: How confident can the seller be that this buyer will close, and how soon will they know? Full loan approval, a meaningful deposit and deadlines the buyer can actually meet all count here.
- Plan: Do the terms fit what the seller has to do next, whether that is moving, buying another home or closing out an estate?
A buyer who can't lead on price can still compete on proof and plan. Price is the easiest of the three to focus on because it is the only one you can see from the listing. The other two require asking questions.
Why the seller's reason for selling changes what "plan" means
The term that matters most to a seller depends on why they are selling. Our team's work on the seller side includes more than 250 senior relocations and more than 100 probate and inherited-property sales, and that work shapes how we read a seller's situation when we represent buyers. The categories below are not rules. They are a starting point for the questions worth asking the listing agent.
- Sellers relocating or downsizing: The move itself can be the hard part. Timing of the closing date and time to stay after closing may matter as much as price, especially when the seller is coordinating a move into a new residence. Sue Kull, SRES®, a Seniors Real Estate Specialist, works with sellers in this situation.
- Estate or inherited-property sellers: The people selling may not live in the home and may have no need to stay after closing. Simple terms, a clear timeline and a reasonable approach to repair requests may matter more to them. Who can sign and when is set by the estate's documents and the estate's attorney, not by the agents.
- Sellers buying another home: A closing date that lines up with their purchase, or a short post-closing stay, can solve a real problem. That is exactly what made the difference for Stephen and Vanessa.
- Sales connected to divorce: Who can accept an offer, and on what terms, may be governed by a settlement agreement, a court order and the parties' attorneys. Clean, clearly written terms can be easier for everyone involved to review.
Three ways to strengthen your offer beyond price
When Sue and I work with a buyer who isn't leading on price, these are the three areas we look at with them.
1. Shorten the timeline to certainty
A long inspection window and a slow loan approval leave the seller waiting and worrying. When your lender has you fully approved up front, not just pre-qualified, you may be able to agree to a shorter inspection period and a faster loan approval. How short is realistic depends on your lender, your loan type and the property. We always tell our buyers to ask their lender what is realistic before shortening any deadline, because a deadline you can't meet puts your deposit at risk.
2. Ask what the seller actually needs
Price is only one part of a seller's decision. They may need a specific closing date, time to stay after closing, help with moving, or flexibility on items left in the home. That is why we suggest a short, respectful call to the listing agent before you write the offer. In Stephen and Vanessa's case, that one call uncovered the term that won them the house.
3. Make your terms easy to say yes to
A clean offer with clear deadlines, proof of funds or full approval, and terms that fit the seller's plans gives the seller less to question, and it can compare well against a higher offer full of open questions. If you agree to something like a post-closing stay, we recommend putting it in a written occupancy agreement that covers the length of stay, who pays utilities, insurance, the condition of the home at move-out and what happens if the sellers stay late. Your lender may also limit how long a seller can stay after closing, so check with them first.
What this means if you're buying now
The highest price is not the only way to compete. Being clear, prepared and responsive to what the seller needs can make a lower offer the stronger one, though no approach guarantees the seller will choose you. We help our buyers get fully approved before they shop, find out what the seller needs, and write offers aimed at the seller's concerns. This is negotiation as problem-solving, not pressure, and it is the approach I bring as a Real Estate Negotiation Expert (RENE).
Before you write your next offer, you can explore The Kull Group's guidance for buyers and sellers in Palm Beach County and the Palm Beach-to-Port St. Lucie corridor, including how the seller-side situations above shape what a seller is looking for.
Frequently asked questions
Can a financed offer really beat a cash offer?
Yes, it can. A cash offer with no financing contingency removes the risk of a loan denial, which is a real advantage. A financed buyer who is fully approved and agrees to short, realistic deadlines can narrow that gap, depending on the lender, the loan type, the appraisal and the contract terms. If the financed offer also solves a seller's problem, such as a needed post-closing stay or a specific closing date, it can win even at a lower price. Stephen and Vanessa's Loxahatchee purchase is one example.
Who should I call to help me win a home in Palm Beach County?
Call or text Chris and Sue Kull at 561-440-0777. We have been in real estate since 1994, and we'll walk you through how to make your next offer as competitive as your situation allows.
Chris Kull, RENE, and Sue Kull, SRES®, are Florida REALTORS® with The Kull Group powered by Keller Williams Wellington. Lending programs are offered by independent lenders and are subject to credit approval and program terms. This article is general information, not legal, lending or tax advice. Consult the appropriate attorney, lender or other professional about your situation.
See This Month's Seven City Snapshot
Search homes in the Seven City Snapshot: